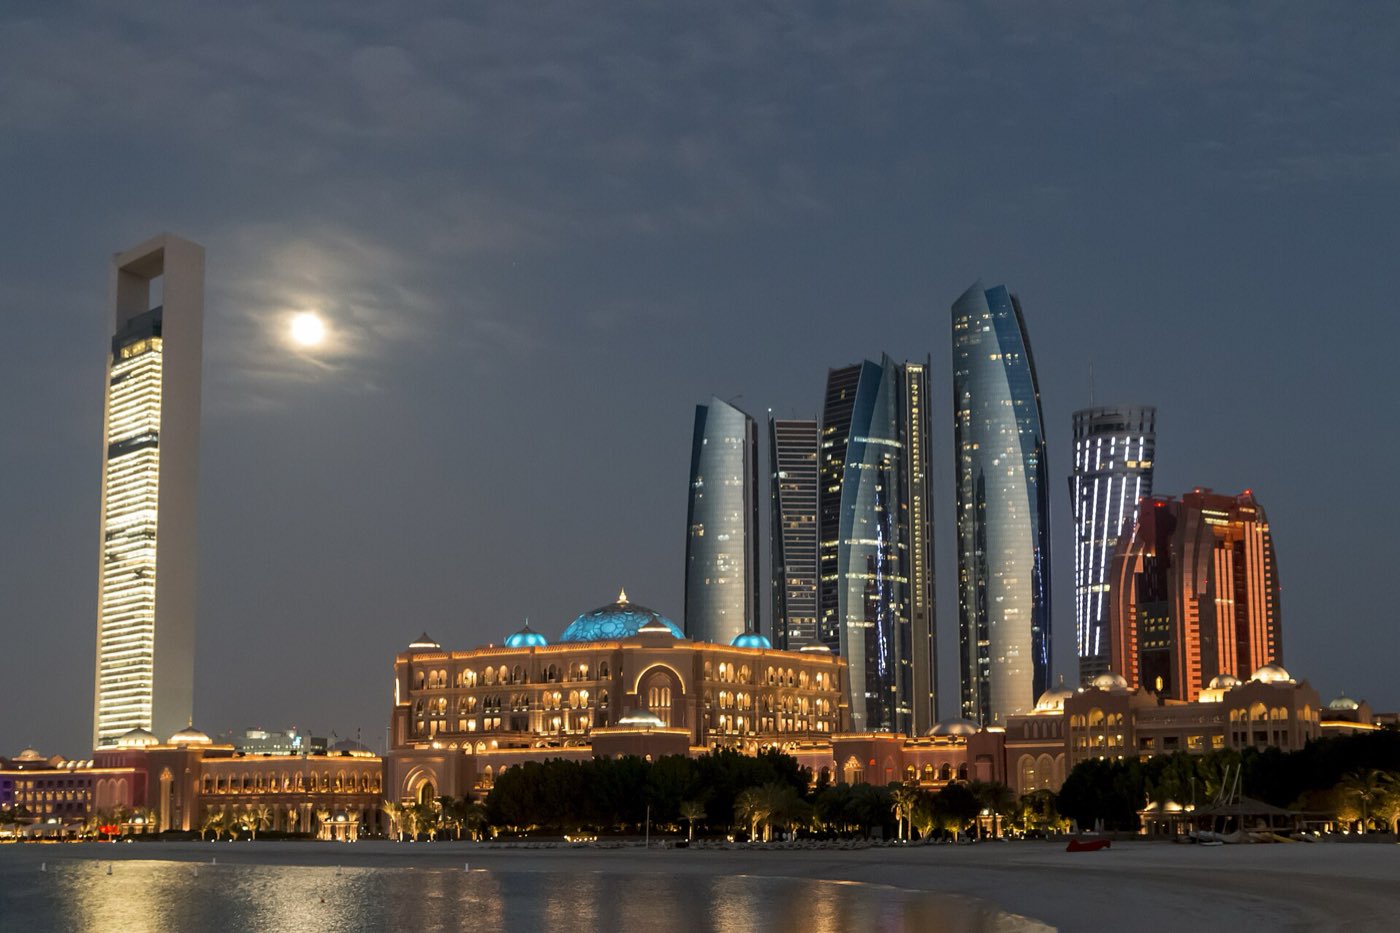
01 · The re-rating
Perception versus the data
A market for civil servants and oil executives, not investment capital. That was the story. These are the figures from ADREC, the emirate's regulator, and ValuStrat's price index.
- Q1 2026 transactions
- AED 66bn ▲ 160.7%
- H1 2026 transactions
- AED 117bn ▲ 112%
- Residential values
- +17.8% Year on year, Q1
- Apartment values
- +22.7% ▲ 10.4% in the quarter
- Villa values
- +13.4% Slower, steadier
- FDI, Q1 alone
- AED 8.27bn ▲ 423%
- Nationalities buying
- 99 ▲ from 68
- Citywide occupancy
- 88.1% Rented stock
Foreign direct investment in Q1 2026 alone, AED 8.27 billion, was roughly equal to the whole of 2025 combined. Across the half year it reached AED 13.8 billion and beat the full prior year outright. That is not a sleepy market. It is a market re-rating in real time.
02 · Claim one
"It's only for end-users"
The old assumption is that Abu Dhabi property gets bought and lived in, not bought for income. The transaction mix says otherwise: off-plan made up roughly 90% of sales value and more than 80% of homes purchased in Q1 2026. That is investor-scale capital, not first-home buying.
Gross rental yields by area
Indicative gross yields on apartments, 2026, % per year
View as table
| Area | Gross yield | Character |
|---|---|---|
| Al Reef | 9.0–9.5% | Affordable, high income |
| Al Ghadeer | 8.0–8.5% | Affordable, border location |
| Masdar City | 8.0–8.5% | Corporate tenant demand |
| Yas Island | 6.0–9.0% | Lifestyle and short-let |
| Al Reem Island | 6.0–8.0% | Deepest rental liquidity |
| Saadiyat Island | 4.5–5.5% | Capital growth, not income |
Notice that the highest yields are not on the famous islands. Al Reef, Al Ghadeer and Masdar City lead because entry prices are far lower while rental demand stays firm. Saadiyat sits at the bottom precisely because it is a capital-growth asset.
These are gross figures drawn from listing data. Service charges take a real bite out of them — roughly AED 25–45 per sqft on Al Reem, which is what turns 6–8% gross into 5.7–6.6% net. Ask for the net number on the specific building before you buy anything on a yield claim.
03 · Claim two
"Everyone's just buying Saadiyat and Yas"
Saadiyat and Yas built Abu Dhabi's reputation. They are no longer where the money actually goes. Hudayriyat has topped the emirate by transaction value for two consecutive quarters.
Residential sales value by area
H1 2026, AED billions
View as table
| Area | H1 2026 sales value | Share |
|---|---|---|
| Hudayriyat Island | AED 19.0bn | 27% |
| Saadiyat Island | AED 13.3bn | — |
| Al Reem & Al Maryah | AED 10.5bn | — |
| Yas Island | AED 7.3bn | — |
Hudayriyat leads on value; Al Reem leads on volume. One is where the largest cheques are written, the other is where the most deals happen. Together with Saadiyat and Yas, those four areas took about 67% of all sales and 65% of all sales value in H1 2026.
Modon's Bashayer launch on Hudayriyat sold out in a single day in December 2025 for close to AED 3 billion. Eagle Hills is selling Ramhan villas from AED 6.4 million with no completed units on the island at all — investors are committing well ahead of delivery on the right address.
04 · Claim three
"Growth is slower than Dubai"
Not on the percentages. Abu Dhabi residential values rose 17.8% year on year to Q1 2026 on ValuStrat's index, with apartments at 22.7%. Dubai's comparable CBRE figure sits around 13%.
Abu Dhabi is growing off a much smaller base. In Q1 2026 Dubai recorded AED 252 billion of transactions against Abu Dhabi's AED 66 billion — Dubai is close to four times larger, and its resale market is far deeper. Abu Dhabi's entire secondary market ran to just 7,658 resale transactions in 2025.
Faster growth on a smaller market is not the same claim as a bigger market. Both facts are true and you should hold them together rather than picking whichever one fits a pitch. Dubai wins on liquidity and exit; Abu Dhabi wins on entry price and current pace.
05 · The mechanism
What is actually holding supply back
Two structural constraints explain most of the price movement, and both point the same way.
2026 residential supply: planned versus likely
Abu Dhabi, units
View as table
| Measure | Units | Gap |
|---|---|---|
| Announced 2026 pipeline | 15,900 | — |
| Realistic handovers | ~8,400 | −46% |
Supply keeps slipping
The 2026 pipeline points to roughly 15,900 units, but on recent delivery trends Cavendish Maxwell and ValuStrat put realistic handovers nearer 8,400 — about 46% below plan. Actual Q2 2026 handovers came in at 1,396 units. Developers are phasing contract awards to match delivery to demand, which supports pricing rather than flooding it.
Freehold access is restricted
Foreign ownership is confined to designated investment zones. Eight new zones were approved in H1 2026, taking the total to around 50, but a substantial share of the emirate remains closed to non-Emirati buyers. Available freehold stock is genuinely scarce relative to demand, rather than artificially withheld.
06 · The forecast
What 2026 is expected to do — and one number to stop repeating
ValuStrat forecasts 16% capital growth for full-year 2026, up from 13% the year before, with apartments continuing to outpace villas.
Capital values versus rents
Abu Dhabi, year-on-year change to Q1 2026
View as table
| Measure | Index | Annual change |
|---|---|---|
| Capital values | 148.0 | +17.8% |
| Rents | 128.1 | +5.9% |
You will see it claimed that Abu Dhabi rents are climbing around 16% a year. They are not. ValuStrat's rental index rose 5.9% year on year to Q1 2026 and was flat quarter on quarter. The 16% figure is the capital growth forecast, repeated in the wrong sentence.
The distinction decides real money. Prices are rising roughly three times faster than rents, which means yields are compressing, not expanding. If you model your return on 16% rental growth you will be badly wrong. Buy on today's achievable rent, not on a forecast that belongs to a different column.
07 · What is coming
The pipeline behind the pricing
Guggenheim Abu Dhabi · 11 December 2026
The largest Guggenheim in the world completes Saadiyat's Cultural District, alongside Louvre Abu Dhabi and Zayed National Museum, which opened 3 December 2025.
Sphere Abu Dhabi · targeting end of 2029
A $1.7 billion, 20,000-capacity venue on Yas Island, the first Sphere outside the United States.
Disney Abu Dhabi · early 2030s
Announced with Miral in May 2025, with the Yas North site confirmed in January 2026. No official opening date has been published, so treat the early 2030s as the realistic read.
Al Maryah expansion · works begin 2026
Mubadala and Aldar's AED 60 billion joint venture adds 450,000 sqm of Grade A offices and 3,000+ waterfront homes, roughly doubling the financial district's office supply.
08 · The practical part
How to position, if you are buying
Structure the Golden Visa around paid-in equity
The threshold is AED 2 million, and on a financed purchase Abu Dhabi assesses what you have actually paid in, not the gross price. A mortgaged AED 5 million property needs the outstanding loan below AED 3 million to qualify. Worth structuring deliberately if you are not paying cash.
Decide income or growth before you pick an area
The spread runs from 4.5% on Saadiyat to 9.5% in Al Reef, and the areas paying the most are not the ones with the famous names. Pick the objective first, then the postcode — doing it the other way round is how people end up with a trophy address and a disappointing return.
Assume the handover slips
With deliveries running around 46% below pipeline, build delay into your model rather than treating the brochure date as fact. That is good for prices and awkward for anyone who needed the rent to start on schedule.
Check the exit before the entry
Abu Dhabi's secondary market recorded just 7,658 resales in all of 2025. Entry pricing is the attraction here; liquidity is the weak point. If you may need to sell within a few years, weight that heavily.
Your move
Where does your budget actually work hardest?
This is the market-level picture. What it cannot tell you is which specific projects are priced well this month, what the real service charges are, or which handover dates are credible. Tell me your budget and whether you are optimising for yield, growth or an easier exit, and I will come back with live inventory and the net numbers rather than another market report.